Written by Julien Ricciarelli-Bonnal
16 November 2026
The Essentials
OpenAI launched ChatGPT Wallet on 13 November 2026, enabling AI agents to complete purchases using payment credentials that keep customers’ actual card details hidden. The service is rolling out gradually through Dots to eligible US ChatGPT Pro subscribers, with biometric approval still required for every transaction. Merchants remain the sellers, responsible for fulfilment and customer service. What changes is the participant navigating the buying process: software can now take an authorised purchase through to payment. Businesses must therefore consider not only whether agents can discover their products, but whether their websites and payment systems can recognise and process legitimate agent-driven orders.
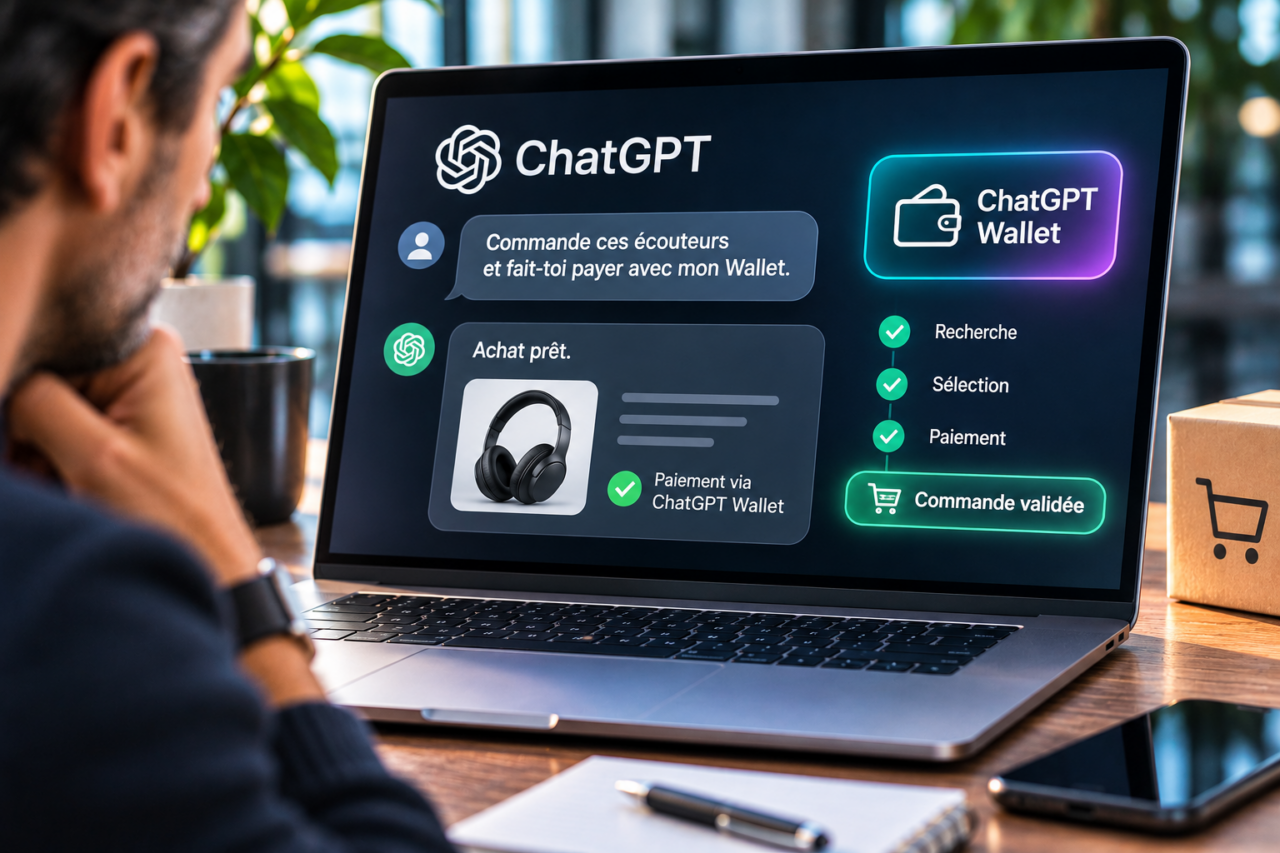
A shopper has found the right product, compared prices and decided to buy. Until recently, even when an AI assistant had done most of the research, payment generally marked the point where the person had to take over: open the retailer’s site, enter details and complete checkout. On 13 November 2026, OpenAI introduced ChatGPT Wallet, allowing its agents to carry out that final step using a payment credential linked to the customer’s card. This may sound like a small interface change, but it moves AI from advising on a purchase towards executing part of the transaction itself.
The launch is deliberately limited. Wallet is rolling out through Dots, OpenAI’s personal agent experience, to eligible ChatGPT Pro subscribers aged 18 or older in the United States, with qualifying US-issued cards and billing addresses. It is not a feature available in every ordinary ChatGPT conversation. Each purchase currently requires the customer to review and approve the transaction. An AI agent is not being given unlimited freedom to spend money; it is gaining a controlled way to complete an instruction the customer has authorised.
This is different from Google’s recent work on purchasing inside its own AI experiences. Google is developing ways for participating merchants to complete transactions within an AI shopping environment. OpenAI’s new wallet focuses on giving an agent payment credentials that existing merchant checkouts can process. For retailers, the distinction matters because the immediate challenge is not necessarily to create an entirely new storefront. It is to make an established commercial system work reliably when the shopper arriving at checkout is software acting for a person.
A payment credential without handing over the original card
The process starts with a card saved securely for Wallet use. When the agent is ready to purchase, the customer reviews the merchant, selected items, total and payment card. Approval then requires a security check such as Face ID or a fingerprint. OpenAI says this produces a record of the particular purchase the user authorised. The step is important because a request to find a good product is not automatically permission to pay whatever price an agent encounters along the way.
After approval, the payment network supplies a tokenised credential instead of exposing the actual card number. The credential can be used in the checkout process, with the charge ultimately applied to the customer’s selected card. Under the arrangement described by OpenAI, neither the agent nor the retailer receives the original card details. Eligible card rewards and protections for qualifying disputes remain in place. Wallet is not a new bank account, stored cash balance or form of credit; it is another way of using an existing payment instrument.
That distinction helps define the autonomy involved. At launch, the agent can navigate commercial steps and present a payment for confirmation, but a human must still approve each purchase. OpenAI has discussed a possible later stage in which users could authorise spending in advance within defined budgets, categories or time periods. Such delegation would be a materially different commercial arrangement. It remains a future direction rather than a general capability available to today’s Wallet users.
Retail checkout was designed for people, not their representatives
Online retailers have spent years improving a journey built around human behaviour: product pages, baskets, addresses, delivery options, card forms and confirmation screens. An agent that can navigate those steps changes who performs the work without necessarily changing the underlying transaction. For some purchases, the customer may now delegate the administrative effort of moving from an identified product to a completed order. The commercial system remains familiar, while the entity interacting with it is no longer the end customer directly.
OpenAI says Wallet is designed to work with existing payment and checkout infrastructure. Merchants do not need a dedicated plugin simply to allow an agent to browse a compatible website. They may nevertheless develop additional interfaces for checking stock, assembling baskets or making specific tasks easier. This approach matters particularly to smaller sellers who could not afford a separate integration with every new AI platform. The initial promise is access through existing commerce arrangements rather than a wholesale replacement of them.
Practical obstacles are already visible. Security systems may mistake legitimate agent browsing for unwanted automation, while fraud tools can flag authorised transactions as suspicious. OpenAI recommends that businesses recognise signed agent requests and work with payment and risk providers to reduce unnecessary failures. That creates an unusual problem: a retailer could have the right product, a willing buyer and valid payment approval, yet still lose the order because its infrastructure does not recognise the way it arrived.
The seller keeps the contract while the agent shapes the journey
OpenAI is not becoming the seller of products purchased through Wallet. The merchant remains responsible for pricing, delivery, returns and customer service, while card issuers and networks retain their part in assessing payment transactions. This allocation matters because the purchaser’s rights do not disappear when an agent handles checkout. If an item is defective or never arrives, the customer is still dealing with a merchant transaction and whatever contractual or card protections apply.
What changes is who organises the purchasing process. A person can ask an agent to find something meeting several constraints without browsing every retailer’s website. The agent can compare available information, narrow the possibilities and attempt to place the order. Merchants may receive a sale without controlling every moment of the customer’s attention. The product is being considered, but the business’s carefully designed path from advertisement to checkout is no longer necessarily the route the buyer follows.
This does not eliminate the commercial value of a brand. Reliability, recognisable quality, credible product specifications and after-sales service remain reasons to choose one seller over another. Yet those strengths must be legible when an intermediary translates a customer’s needs into comparable criteria. For a small business, precise and consistent product information may become as important as the visual presentation of its storefront. Discovery is increasingly influenced by systems that may not reproduce the brand experience the retailer intended.
A confirmed payment makes accountability more concrete
There is a significant distance between a mistaken recommendation and an incorrect order. The first can be ignored. The second can commit money, inventory and delivery resources, even when a refund may ultimately be available. A biometric approval provides an important record, but it does not resolve every conceivable disagreement. A customer might approve a purchase whose product variant was misunderstood, whose delivery conditions were overlooked or whose description did not match expectations. The outcome will depend on the transaction and the rules governing it.
These questions connect with the broader issue of who bears the cost when an AI agent’s actions have financial consequences. Wallet makes that discussion less hypothetical. The agent is not merely drafting text or analysing a spreadsheet: it is taking part in a retail transaction on the user’s behalf. A mistake that once meant an unsuitable recommendation can now appear as an order requiring cancellation, support or a dispute process.
A future shift towards pre-authorised spending would sharpen the problem. Approving one purchase after reviewing a specific amount is not the same as granting an agent permission to buy repeatedly within a budget. The distinction is familiar to organisations developing clear AI permissions, supervision and operational accountability. Deciding which activities can proceed automatically, which require immediate approval and which should be prohibited is ultimately a question about delegated authority, not simply about the sophistication of the software.
The lasting change may be quieter than the idea of AI shopping independently. A new participant can now search, compare and present a secure payment to a merchant. The customer retains purchasing authority, the retailer keeps its contractual responsibilities and the banking system continues to check transactions. But some of the commercial work connecting them is being performed by an agent. For businesses, that redistribution of tasks may matter more than whether the final checkout button is pressed by a person or by software.
Written by Julien Ricciarelli-Bonnal
16 November 2026